Category: Bookkeeping

  • Rules of Debit and Credit Definition, Explanation and Examples

    normal debit balance

    The concept of a normal balance for each account type is integral to the coherence of financial records. It refers to the side of the ledger—debit or credit—where the balance of the account is customarily found. For asset and expense accounts, this is typically a debit balance, while liability, equity, and revenue accounts usually have a credit balance.

    Beyond the Basics: Advanced Concepts Linked to Debit Balances

    By recording transactions as debits or credits correctly, companies ensure their financial reports are accurate. It also helps meet rules set by the International Accounting Standards Board (IASB) and the IRS. When a financial transaction occurs, it affects at least two accounts. For example, purchase of machinery for cash is a financial transaction that increases machinery and decreases cash because machinery comes in and cash goes out of the business.

    Debits and Credits Outline

    Debits and credits represent the left and right side of the account, respectively. This is because gain and revenue accounts normally have a positive account balance. You can use a T-account to illustrate the effects of debits and credits on the expense account.

    normal debit balance

    AUD CPA Practice Questions: Testing Ending Inventory Quantities

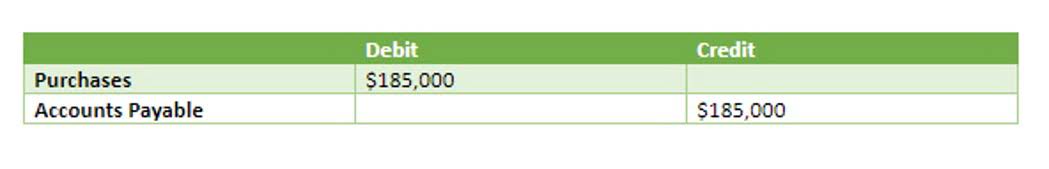
    • These are the main types of services that are noted in the accounts payable.
    • They show changes in accounts within the bookkeeping system.
    • An account in the general ledger, such as Cash, Accounts Payable, Sales, Advertising Expense, etc.
    • When I purchase something, it means exchanging resources for an asset.
    • Liabilities are what a company owes, like Accounts Payable and Notes Payable, and rise with credits.

    Therefore, always consult with accounting and tax professionals for assistance with your specific circumstances. One of the main financial statements is the balance sheet (also known as the statement of financial position). In accounting, the normal balance of an account is the type of net balance that it should have. Above example shows credit balance in creditor’s account (To Balance c/d) which is shown on the debit side.

    normal debit balance

    The main products for which accounts payables are used by companies are raw materials, production equipment, and utilities. These are the main types of products for which companies have accounts payables. The revenue is shown as the credit side http://xlegio.ru/throwing-machines/asia/chinese-pre-gunpowder-artillery/summary.html on the normal balance. Sometimes, the profit from selling the product from the supplier is also debited by the company.

    normal debit balance

    Revenues

    • Property management accounting is simply the financial process involved in managing rental properties.
    • Expense accounts should be reviewed regularly, at least monthly, to ensure accuracy and timely identification of any discrepancies or areas of overspending.
    • Following best practices in accounting is crucial for accurate financial records.
    • It is paid out of the company’s retained earnings or free reserves and since it reduces the balance of reserves it is “Debited”.
    • Conversely, liability, equity, and revenue accounts typically have a normal credit balance.
    • By aligning your expense tracking with these best practices and ensuring your accounting records are kept in an appropriate format, you etch a roadmap to financial clarity and compliance.

    They easily memorized that asset accounts should normally have debit balances, and those debit balances will increase with a debit entry and will decrease with a credit entry. They also memorized that liability and owner’s (or stockholders’) equity accounts normally have credit balances that increase with a credit entry and decrease with a debit entry. It was easy to accept that every transaction will affect a minimum of two accounts and that every transaction’s debit amounts http://xlegio.ru/sources/onasander/preface.html must be equal to the credit amounts.

    • This makes the company’s financial activities clear and strengthens its financial reports.
    • On the other hand, the cash account decreases because of this purchase, so it gets credited.
    • Knowing the normal balance of an account helps maintain accurate financial records, prepare financial statements, and identify errors in the accounting system.
    • The same rules apply to all asset, liability, and capital accounts.
    • Balance Sheet accounts are assets, liabilities and equity.
    • Eric also creates free accounting resources, including manuals, spreadsheet trackers, and templates, to support small business owners.

    The terms are often abbreviated to DR which originates from the Latin ‘Debere’ meaning to owe and CR from the Latin ‘Credere’ meaning to believe. The rest of the accounts to the right of the Beginning Equity amount, are either going to increase or decrease owner’s equity. Based on the rules of debit and credit (debit means left, credit means right), we can determine that Assets (on the left of the equation, the debit side) have a Normal Debit Balance.

    normal debit balance

    It would be quite unusual for any of these accounts to have a debit balance. Ed’s inventory would have an ending debit balance http://putevodka.tv/?sct=685 of $40,000 and a debit balance in cash of $15,000. These are both asset accounts.He would debit inventory for $10,000 due to the new inventory and credit cash for $10,000 due to the cost.

  • Fiscal Year Vs Calendar Year: What’s Best for Your Business?

    You need to file the request with the federal government generally and the IRS specifically. A fiscal year is a year in which business organizations/ firms/ companies/ entities prefer preparing their financial reports for the year. In a fiscal year reporting method, companies may choose to prepare their financial statements on a different twelve-month basis and not the same as the calendar year. The similarity between these years is that these last for 365 days or twelve consecutive months. The calendar year begins on the first of January and ends on 31st December every year, while the fiscal year can begin on any day of the year but will end on exactly the 365th day of that year. Both these years have a total period of twelve consecutive months.

    More in ‘Business’

    Companies can strategically time major expenses to maximize tax deductions. Generally, a year denotes 12 months, with about 365 days and 366 days if it is a leap year. We hear about the terms of the fiscal year and calendar year, but many of us don’t even know what it represents and the differences between them. For individual and corporate taxation purposes, the calendar year commonly coincides with the fiscal year and thus generally comprises all of the year’s financial information used to calculate income tax payable.

    Can you change your tax year with the IRS?

    After that, it’s considered that you’ve already made your choice, and you have to get special permission from the IRS to change, using Form 1128, Application to Adopt, Change or Retain a Tax Year. While the fiscal year can run from any time in the year provided it has 365 days, the calendar year runs from 1st January to 31st December. In summary, the fiscal year focuses on financial matters, while the calendar year is a broader measure of time used in everyday life. But this July to June financial year does not apply in all countries. Many align their financial year with the calendar year, but others have further variations still.

    This knowledge can aid in better financial planning and alignment with government processes, benefiting both taxpayers and companies contracting with the government. The federal government’s fiscal year is a twelve-month period used for accounting purposes, running from October 1 to September 30 of the following year. This structure aligns federal budgeting processes with the operational needs of government agencies, facilitating effective fiscal planning. This period is part of the federal government’s fiscal calendar, which is distinct from the traditional calendar year. This twelve-month period is essential for federal budgeting, tax filings, and difference between calendar and fiscal year financial reporting.

    • For instance, if the year begins on the 1st of April, it will end on the 31st of March next year.
    • Whether an entity opts for a fiscal year or adheres to the traditional calendar year, careful planning and alignment with stakeholders are essential for success.
    • On the other hand, a calendar year follows the traditional January 1st to December 31st timeframe.
    • As with a fiscal year, a calendar year also describes a consecutive twelve-month period.
    • In summary, a fiscal year is a critical component of financial management, used by businesses, governments, and organizations for financial reporting, budgeting, and accounting.
    • The similarity between these years is that these last for 365 days or twelve consecutive months.

    Dates

    The British empire also influenced the April reporting schedule in India, as prior to independence many financial policies were based on the British system. In contrast to our own, the United Kingdom’s financial year starts on April 6 each year and runs to April 5 the next. Companies need to consider the impact on financial comparisons, stakeholder communications, and internal systems adjustments.

    For example, a company with a fiscal year ending June 30 would need to file its tax return by October 15. Unlike the calendar year, which always begins on Jan. 1 and ends on Dec. 31, a fiscal year can start and end in any month. As with a fiscal year, a calendar year also describes a consecutive twelve-month period. However, it begins on New Year’s Day and ends on the last day of the year. For countries like the United States that follow the Gregorian calendar, this means it begins on Jan. 1 and ends on Dec. 31. Businesses using the calendar year for financial reporting will prepare their statements based on transactions taking place between these dates.

    Before setting the fiscal period, companies may consider financial reporting deadlines, tax season or even business statistics. In conclusion, the federal fiscal year offers significant advantages over the traditional calendar year, providing flexibility, efficiency, and better alignment with federal budgeting processes. By understanding this financial cycle, individuals and businesses can better navigate the complexities of government operations and make more informed financial decisions. The federal fiscal year is divided into four fiscal quarters, each lasting three months, aiding in structured financial planning and management.

    Tax-Loss Harvesting

    Today is July 1, the first day of the new financial year in Australia. While many fiscal years begin from the first of a particular month, they can also begin at other dates, such as during the middle of the month. Individuals who file using the calendar year must continue to do so even if they begin operating a business, sole proprietorship, or become an S corporation shareholder. Implementing a fiscal year can increase your business’s visibility to your accountant. Tax preparation firms are typically busiest from January to April.

    For example, a company’s Fiscal Year 2025 (often abbreviated as FY2025 or FY25) may run from Feb. 1, 2025, to Jan. 31, 2026. This naming convention helps maintain clarity and consistency in financial communications and reporting. Perhaps the biggest advantage of using the calendar year is simplicity. For sole proprietors and small businesses, tax reporting is often easier when the business’s tax year matches up with that of the business owner. Moreover, while any sole proprietor or business may adopt the calendar year as its fiscal year, the IRS imposes specific requirements on those businesses wanting to use a different fiscal year. You must first obtain approval from the Internal Revenue Service (IRS) by filing Form 1128 if you want to switch from the calendar year reporting to fiscal year reporting for your tax filings.

    Typically, the President submits a budget proposal to Congress in February, outlining spending plans for the upcoming fiscal year. Financial years allow income and expenses to be tracked and compared over the same timeframe each year. This allows investors to compare business performance across consistent periods. They are also used to determine the collection of personal income tax. The decision to adopt a fiscal year and when should be based on carefully considering an organization’s specific circumstances, including its industry patterns, operational cycles, and strategic objectives.

    What is the federal government’s fiscal year?

    • For retailers, having a fiscal year that includes the holiday season is particularly advantageous.
    • Usually, its only large corporations that do — the IRS actually places restrictions on any other entities electing to use a fiscal year, and only allows it when certain conditions are met.
    • It is the standard calendar used worldwide for tracking dates and planning activities.
    • India’s fiscal year runs from April 1 until March 31, for a number of reasons.
    • The federal budget process for the upcoming fiscal year begins a year in advance, involving various government agencies and ultimately Congress.

    Unlike the calendar year, which runs from January 1 to December 31, a fiscal year can start and end on any date, providing flexibility in financial management. Federal agencies also rely on the fiscal year to manage their financial resources and allocate funds for various programs and activities. Aligning the accounting period with the federal government’s fiscal year ensures consistent financial reporting and budgeting across the government. On the other hand, a calendar year follows the traditional January 1st to December 31st timeframe. It is the standard calendar used worldwide for tracking dates and planning activities. While most individuals and entities use the calendar year for personal and administrative purposes, some prefer a fiscal year for financial clarity and strategic decision-making.

    Under IRS rules, a tax return is usually due on the 15th day of the fourth month after the end of the tax year. A calendar year, obviously, runs from January 1 to December 31, just like the calendar on your wall. A fiscal year is any twelve-month period that begins and ends differently than the calendar. For example, the fiscal year for schools is usually July 1 to June 30.

    To find the start date of a fiscal year, add one day to the end date and then go back a full year. If the last day of a fiscal year is August 31, 2017, adding one day will take us to September 1, 2017. Going back a full year results in September 1, 2016, which is the start day of that fiscal year. Our government uses this information to calculate the amount of tax it will collect through the Australian Taxation Office each year.

    Changing from a calendar year to a fiscal year (or, changing an established fiscal year) requires careful planning and consideration. Organizations must file Form 1128 with the IRS to request approval for the change. This transition period, known as a short tax year, requires special handling of financial statements and tax calculations.

    A calendar year for individuals and many companies is used as the fiscal year, or the one-year period on which their payable taxes are calculated. Some companies choose to report their taxes based on a fiscal year. In most cases, this period starts on April 1 and ends on March 31, and better conforms to seasonality patterns or other accounting concerns applicable to their businesses. A fiscal year enables organizations to better match their financial reporting with their operational patterns.

    Corporations adopt different fiscal years based on their specific business needs. For example, Apple Inc. ends its fiscal year on the last Saturday of September, while Microsoft Corporation ends its fiscal year on the last day of June. Macy’s Inc., on the other hand, ends its fiscal year on the Saturday closest to January 31. In the United States, fiscal years once ran from July 1 to June 30, like Australia’s do now. But in 1974 this was changed to instead span October 1 to September 30, giving Congress more time to agree on a budget each year. But the calendar year, based on the Gregorian calendar, runs from New Years’ Day on January 1 through to December 31.

  • Solved: Free QuickBooks Online Software for Teachers and Students

    Pricing normally starts at $30 per month for the Simple Start, but you can save some money if you sign up now. As previously stated by my colleagues above, QBO offers a free 30-day trial that gives you full access to all the popular accounting features and benefits included in your chosen plan. This will also be a great opportunity to experience how QuickBooks simplifies your bookkeeping.

    • A member of our support team is ready and available to answer your QuickBooks questions.
    • Write your comments below if you have other inquiries about using QuickBooks as your accounting tools.
    • I could say QB Online Accountant version is a free version of QB Online.
    • You can always check your Account and Settings section on how many days you have left until the trial expires to ensure your account stays active.

    I can give information about the class listing and the university showing me as instructor. Once you sign up for the Intuit Education program, both the educators and students should complete the form to confirm eligibility and unlock the free license for QuickBooks Online. Can you please give me this same information for quickbooks online free and how to test for ceritification only. Everything is organized in its place the way it should be. I appreciate how it tracks clients/customers, tracks payments, and keeps running calculations of what is due and when.

    Can I have QuickBooks without a subscription?

    QuickBooks Online is great for businesses who need access to their business data from anywhere and real-time collaboration. Move your accounting online to take advantage of automatic data backup, live insights from your accountant, automated workflows to reduce errors and increase efficiency, and reports that are tailored to your business. I tried calling support but you can’t speak to a person if you don’t have an account, and the chat option isn’t working either. I need to access this fairly soon or I’ll need to scrap the class project using QuickBooks and substitute another accounting software. I would prefer to use QBO since QB is the choice of most small businesses and I’m familiar with it.

    There are programs out there that may be fantastic programs but can also be dangerous. For example, Acrobat Pro has been known to get into chaos at times. The form for high school students does not have our high school listed. I have emailed Intuit asking them to add it so I can register them but no response and the chat support does not help either. Leave your comments below if you have other questions about using QuickBooks as your tool in advancing the accounting knowledge of your students.

    Frequently asked questions

    It depends on the version you get and the trial that you get that doesn’t cost anything. Becoming a reliable source of information about accounting, tax compliance, and best business practices is one great way to get known in your industry. I also tried to use the information and the link from an email (below) from Intuit confirming my teacher account and about setting up the student accounts, but had technical trouble with the website loading. You don’t even need a credit card to start out with one of the best website builders — Squarespace — so there’s absolutely no risk. All you need to do is pick out a template that works for your needs and go from there.

    Alternatives to the Quickbooks free trial

    • Move your accounting online to take advantage of automatic data backup, live insights from your accountant, automated workflows to reduce errors and increase efficiency, and reports that are tailored to your business.
    • A Live Bookkeeper cannot begin cleaning up your past books until they receive the required supporting documentation, which your bookkeeper will request from you after your first meeting.
    • Yes, it’s possible to extend the trial period for your free QuickBooks Online (QBO) access.
    • QuickBooks gives us real-time insight into our business operations and I appreciate that as it allows us to be more productive.
    • And QuickBooks coupons often bundle multiple softwares, so you end up paying for a second or third product that you’ll hardly use.

    We’ll be completely honest with you — if you’re 100% set on QuickBooks for free (and legal), you’re out of luck. Though there are methods of pirating the software, we don’t recommend any of them. In many cases, it’s far too easy to download malicious files, viruses, or other malware that could permanently damage or compromise your computer. Please feel free to reach out to us with any additional information or questions you may have.

    You are leaving Intuit.

    Microsoft Word is actually part of the company’s wider Office app suite. That means if you want a Microsoft Word free trial, you’ll need to sign up for the Microsoft 365 trial. Of all of the best accounting software suites, QuickBooks arguably stands the tallest. Its long-standing popularity is owed to the fact that QuickBooks is feature-rich, easy to use, and offers a variety of different packages to suit users of all types.

    Free mobile apps

    It can be complicated, but Tech soup offers some helpful videos. We’re here to make migrating your desktop data and getting to know QuickBooks Online as seamless as possible. Easily do it yourself, or get help from a specialist if you have questions.

    If you’re thinking of giving QuickBooks a spin and want to know if you can try it without ponying up any cash first, then read on. We’ll explain everything you need to know about the QuickBooks 30-day free trial, along with some info on how you can save on your subscription if you decide to commit. You can always check your Account and Settings section on how many days you have left until the trial expires to ensure your account stays active. Let me know if you have additional questions about QuickBooks plans and features. Take control of your business by saving time on bookkeeping and paperwork with QuickBooks. QuickBooks gives us real-time insight into our business operations and I appreciate that as it allows us to be more productive.

    Yes, it’s possible to extend the trial period for your free QuickBooks Online (QBO) access. You’ll just have to email a request for a new license with a copy of their class schedule. Please refer to the “Do I qualify for Intuit Education’s Programs?” section of this article for the email to use. Students and teachers can get a free access to QuickBooks Online through our Intuit Education Program (IEP). You can apply and set up your account by visiting our website or sending an email to QuickBooks and Intuit are a technology company, not a bank.

    We also offer expert-led webinars, can i get quickbooks for free easy-to-use guides, and free phone and chat support. These days, a lot of people are trying to cut costs so they can save money and still keep the software running well. This is why it is good to get a free trial and find the software package that fits your budget. Another reason why you might want to consider upgrading a paid version of QuickBooks is that they are considered to be somewhat reliable  to use every single month. Still, most of the companies that offer a free version have a support department that will help you through the process of using the program for as long as you need it. Just make sure that you find a place that you can get help with your problems.

    VPNs can offer a lot of great advantages depending on what sort of things you want to do. For example, if you’re traveling and still want to watch content from back home, they can offer you a way to get around geoblocking that tends to happen. While they aren’t perfect security tools, they’re a great addition to make your life easier, especially since some of the best VPNs include a whole suite of products, including ad blockers. I don’t mean just a free trial — I mean a less expensive per month or free subscription. My business is very simple —- I send invoices, I get paid. While the QuickBooks Online free trial offers all the features included in your chosen plan, it does not include optional add-on features, such as Payroll, Payments, Bill Pay, or Live Expert Services.

    With QuickBooks, you can easily create and send invoices, link your bank accounts for real-time transaction updates, and get a clear snapshot of your business’s financial health at any time. Plus, it’s all accessible in the cloud, meaning you can manage your finances from anywhere—whether you’re at the office, on the go, or enjoying a well-deserved coffee break. Of course, QuickBooks isn’t the only accounting software on the block. In fact, Xero provides a free trial plus 90% off for the first 6 months when you sign up for a subscription which is an attractive offer for businesses looking to save. Xero boasts similar features to QuickBooks, such as invoicing, expense tracking, and financial reporting.

    Alternative to a free Quickbooks trial

    The software is very easy to use, even for people who do not have an accounting background. Use the apps you know and love to keep your business running smoothly. A member of our support team is ready and available to answer your QuickBooks questions. Get instant access to the tools and features you need to drive your business forward with deeper insights, custom workflows, easy collaboration, and more. Come back to this post if you have other concerns or follow-up questions about this.

  • Bookkeeper vs Certified Public Accountant: Whats the Difference Between Them?

    certified public bookkeeper salary

    The bookkeeper job Certified Bookkeeper description entails maintaining the general ledger and accounts, recording transactions, posting debits and credits, running payroll and creating invoices. Before you can become a licensed CPA, you must pass the CPA Exam, and acquire the necessary work experience. Fortunately, many companies and accounting firms hire recent college graduates with accounting degrees who have the ability to become CPAs.

    certified public bookkeeper salary

    Bookkeeper Jobs By Location

    certified public bookkeeper salary

    While bookkeepers record transactions, accountants analyze them and help organizations make decisions based on their findings. The two professions work with many of the same data, accounts, and software, which makes bookkeeping an effective stepping stone into accounting. Bookkeeping has no mandatory educational requirements, but many employers prefer to hire candidates with high school diplomas and some bookkeeping credits at the college level.

    certified public bookkeeper salary

    Certified Public Accountant Related Jobs

    • Intuit provides its employees with supplemental learning materials after training has been completed to assist employees in developing their skills.
    • A bookkeeper’s work may be reviewed by someone inside the company, or by the company’s outside accountant.
    • According to BLS data from May 2021, the top 10% of bookkeepers earned median base salaries of $61,980 per year.
    • They are in charge of recording various transactions like income and outgoings and posting these transactions to different accounts.
    • Intuit is dedicated to providing its employees with the ability to learn and grow throughout their time with our company.
    • The average annual salary for a bookkeeper in the United States is approximately $42,000.

    AIPB offers a series of six self-paced classes and accompanying workbooks, all of which are part of AIPB’s CB what is a bookkeeper preparatory course. AIPB also has extra courses for sale, such as mastering double-entry bookkeeping. Before jumping straight into either exam, you must first take a series of courses. Prior bookkeeping experience does not exempt you from these preparatory courses. Completing courses and workbooks can help you prepare for and pass your bookkeeping exam. You must pay for each part of the required exam, along with any preparation courses you may take.

    What are the salaries of a Bookkeeper with different levels of education?

    However, the CPB path may be better for less experienced bookkeepers as it requires only one year of professional experience. For example, a certification from California State University, Fullerton costs $2,195. As for certification from AIPB, members pay $479, and nonmembers pay $574. The price of this certification includes contra asset account the cost of enrollment, workbooks and the four-part national certification exam. After passing the AIPB’s certification exam, you will be recognized as a certified bookkeeper.

    • While most bookkeepers work with businesses, some individuals may also choose to hire a bookkeeper to track personal finances.
    • The U.S. Bureau of Labor Statistics (BLS) groups bookkeepers with accounting and auditing clerks in its job-related data.
    • To qualify for the CPB certification exam, you must complete NACPB courses in accounting, payroll, and Intuit QuickBooks fundamentals.
    • Salary.com provides salary estimates, histograms, trends, and comparisons using data from employer job postings and third-party sources.
    • As a bookkeeper, your income level may vary based on your location, experience and employer.

    Welcome to the Certified Bookkeeper (CB) Program!

    Requirements for CB certification are more extensive, as they ask for at least 3,000 hours of experience or two years of bookkeeping or accounting experience. Prior to earning either designation, you must prove that you have sufficient bookkeeping experience. In September 2022, Payscale reported an average annual base salary of about $50,430 for full-charge bookkeepers. According to BLS data from May 2021, the top 10% of bookkeepers earned median base salaries of $61,980 per year. Employers in areas with higher living costs also tend to pay a premium.

  • AP Automation How to automate accounts payable + Software

    AP automation

    With the right AP automation software, you can simplify workflows, reduce errors, and optimize payment cycles for your business. QuickBooks reduces manual errors, Cash Flow Management for Small Businesses saves time on repetitive tasks, and enhances payment accuracy. Its real-time visibility into financial data enables you to make informed decisions. NetSuite is ideal for enterprises seeking comprehensive accounts payable automation software with scalability and advanced financial tools.

    • For instance, in a large organization (over 250 employees), handling a single invoice can take days or even weeks.
    • Acumatica’s Accounts Payable software is designed to streamline accounts payable processes and keep outgoing cash flow timely and accurate.
    • Modern AP Automation systems are equipped to handle transactions in multiple currencies and manage payments to international suppliers efficiently.
    • With Tipalti, Endera streamlined invoices, automated vendor onboarding, and improved international payments by eliminating manual wire transfers.
    • This transparency and ease of interaction strengthen vendor collaboration, reducing back-and-forth communication.
    • Being adaptable means regularly reviewing new tools and adjusting workflows to meet evolving business needs.

    Why businesses of all sizes automate accounts payable

    AP automation

    Finance teams get more data-backed insights and can make quick decisions that save money and time or improve performance. If the business is processing a high volume of invoices, the only solution to scaling up operations is to add headcount. Omni Hotels & Resorts, a luxury brand with over 50 properties, faced significant AP challenges amplified by the pandemic.

    • Easy-to-use web-based and mobile applications help you to streamline your AP processes, from on-the-go authorization to supplier payment.
    • Typically, cloud-based solutions charge subscription fees of $500–$2,000 per month for small to mid-sized businesses.
    • Effective accounts payable management helps increase control over the entire payables process — from invoice receipt and approver responsiveness through invoice automation.
    • It will catch if an invoice is outside of the usual cadence, whether there are inconsistencies with vendor or payment information, or if there’s no supporting document like a purchase order.
    • Automatically categorize and code invoices, then route them for approval using hierarchical approval rules.
    • This shift from manual to automated processes is a significant step forward in the evolution of financial management.

    Streamline the entire invoice process with a workflow tool that allows for precise tracking

    AP automation

    AP automation solutions generally include mobile apps for extra accessibility during approval. If you are in charge of payment authorizations, you must be accessible even on the go. And this can lower your processing costs as you don’t have to waste time going into the office to give invoice approval. Accounts payable (AP) automation is a specialized system of accounts payable software designed to help businesses reduce the time spent on invoicing tasks. By automating your payment processes, you can cut down on costly accounting errors and AP automation for manufacturing companies common invoicing delays. MineralTree’s direct integration with banks for payment processing enhances security and streamlines payment.

    AP automation

    Compliance & fraud prevention

    AP automation

    It must handle growing invoice volumes and support various currencies and bookkeeping payment types without major changes. Ensure the software integrates easily with your existing systems like ERP and accounting platforms. Being adaptable means regularly reviewing new tools and adjusting workflows to meet evolving business needs. Sage Intacct also offers Open API, a unique integration that facilitates and simplifies data sharing between Intacct modules and third-party software. Open API expands Intacct’s AP functionality by opening the door to a portfolio of tailored AP automation platforms.

    AP automation

    For Suppliers

    • Your accounts payable automation software eliminates manual invoice processing, lowers the risk of human errors, and prevents late payment penalties.
    • Today’s solutions leverage artificial intelligence and machine learning to identify discrepancies, detect fraud risks, and reduce exceptions before they disrupt workflows.
    • This feature is crucial for businesses operating on a global scale, providing accurate financial reporting and simplifying international payment operations.
    • Before committing to the best accounts payable automation software, test it with a demo or trial period.
    • “Prior to using Centime we were 100% manual on entering and approving all invoices. Centime is a fantastic AP automation tool that streamlined our invoice processing and payment workflows.”

    There’s never been a better time for businesses to transform their payment processes through automation. By shifting your risky paper-based payments to digitally disbursed payment methods like ACH and virtual card transactions, you significantly reduce your chances of being the subject of a successful fraud attempt. Once approved, invoice data is synced with your ERP system in real time—ensuring consistency, accuracy, and audit readiness. Instead of spending precious brain-power trying to make a dent in the never-ending influx of paper — proactively eliminate it from the equation through accounts payable automation. Yes, AP automation software is equipped with robust security measures to deter invoice fraud. Features such as multi-factor authentication protect access to the system, while data validation checks flag inconsistencies in vendor details or invoice amounts.

    Easily extend and simplify your workflows with pre-built integrations and powerful APIs for your ERPs, accounting systems, performance marketing platforms, HRIS, SSO, Slack, credit cards, and more. With AI and machine learning capabilities, an intuitive UX, and quick and easy global payments, you can drive unprecedented efficiency. Our multi-language, self-service supplier onboarding means you’ll capture accurate supplier details, reduce status inquiries, and gain complete visibility. Final payments can also be approved, making the process more secure, but with significantly less friction.